A short family money meeting creates a predictable place for questions, goals, and upcoming choices. It should not expose children to adult burdens or become a performance review. Keep the conversation age-appropriate, practical, and limited to decisions where children can participate.
Quick answer: Meet once a month for about 20 minutes at the same time. Follow five steps in the same order: celebrate one win (3 min), review one goal (5), discuss one upcoming choice with a set budget (5), check allowance and accounts (4), and end with questions and one action (3). Keep adult-only topics such as debt details and account numbers out of the room. Print the checklist below and reuse it.
Why bother at home if schools teach this now? More schools do: the Council for Economic Education’s 2024 Survey of the States found that 35 states require a personal finance course to graduate from high school. That course usually comes late in high school, though. A monthly meeting gives younger kids years of low-stakes practice first, using your family’s real (age-appropriate) decisions.
Before the meeting
- Choose a regular time, such as the first Sunday of each month.
- Keep the meeting to about 20 minutes.
- Bring one shared goal, one upcoming decision, and allowance or savings trackers.
- Leave private account numbers, debt details, and sensitive documents elsewhere.
- Invite each person to bring one question.
20-minute agenda
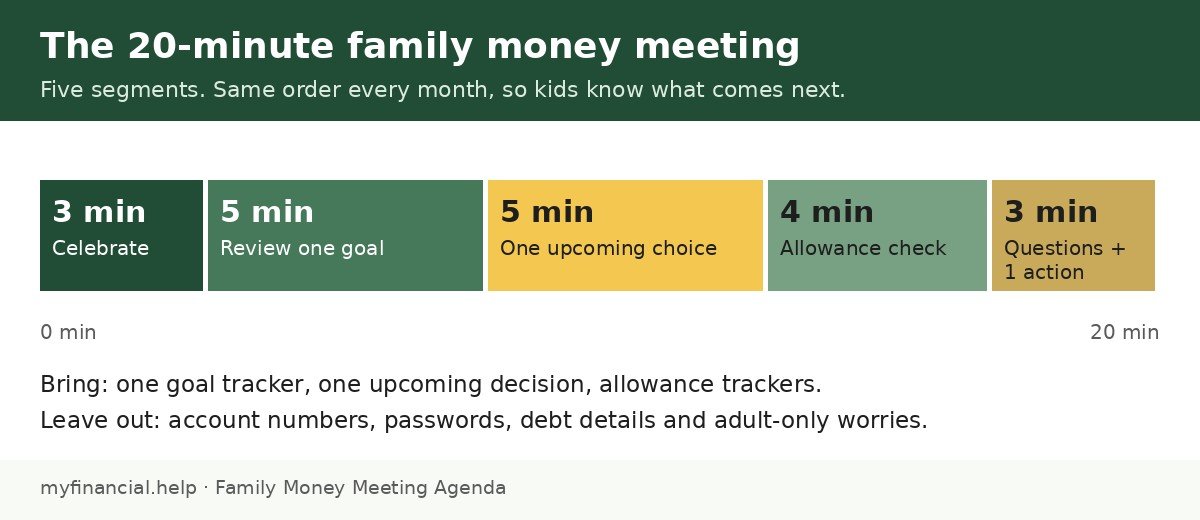
1. Celebrate progress — 3 minutes
Each person names one money habit or choice that went well. Recognize planning, waiting, comparison, honesty, or recovery from a mistake.
2. Review one goal — 5 minutes
Update a family or individual savings goal. Compare current progress with the target and decide whether the amount, deadline, or next action needs to change.
3. Discuss one upcoming choice — 5 minutes
Examples include a family outing, birthday plan, school expense, subscription renewal, or grocery challenge. Give children a defined budget and two or three realistic options.
4. Allowance and account check — 4 minutes
Confirm the next payday, responsibilities, and expenses the child controls. Older children can report balances and unfamiliar transactions without reading private account credentials aloud.
5. Questions and one action — 3 minutes
Answer what you can. If you do not know, model checking a reliable source. End with one action, owner, and date.
Our Family Money Meeting
Suggested ages 6–18 · PDF · 1 page
Use a 20-minute agenda to choose one small family money action.
Who does what, by age
| Age | What they can do in the meeting | Keep with the adults |
|---|---|---|
| 6–8 | Share one win, move a sticker on a goal chart, choose between two outing options | Prices beyond the one decision, any money worries |
| 9–12 | Report their own savings balance, compare two options against a set budget, keep time | Household bills, income details |
| 13–15 | Run one agenda item, check a subscription renewal, explain a tradeoff | Debt details, account credentials |
| 16–18 | Lead the meeting, review their own bank activity, plan a family outing within budget | Anything they would feel responsible for fixing |
Your first three meetings (worked examples)
A blank agenda can stall. Here is one way to run the first three months, each built around one of our free tools. The numbers are examples only.
Meeting 1: pick one family goal
Choose something small and shared, such as a game night supply box or a day trip. Write the target and a date, then decide who contributes what. If a child also has a personal goal, run it through Can My Child Afford It? so the meeting has a clear number to track. Example: a $60 item, $15 already saved, $5 a week → $45 still needed, 9 weeks.
Meeting 2: plan an outing within a limit
Give the kids a budget and let them build the plan in the Family Outing Challenge. Example inputs: $60 budget, 4 people, $8 travel, $32 tickets, $18 food, $8 treats. The tool shows $66 planned, $6 over budget, $16.50 per person, and asks the child to choose which category changes. Cutting treats to $2, or packing snacks to bring food to $12, fixes it. The lesson is the tradeoff, not the cheapest day out.
Meeting 3: check recurring charges
Teens can bring their subscriptions to the Teen Subscription Reality Check. Example inputs: $25 a month in subscriptions, $10 an hour of take-home pay, 5 years, one $9 subscription to consider cutting. Result: $300 a year, $1,500 over 5 years, 30 hours of work a year, and cutting the $9 service keeps $540 over 5 years. Each subscription gets a keep, pause, or cancel decision before its next renewal.
Scripts for the hard moments
- “How much money do you make?” Ask “Why do you want to know?” first. Then share what fits your family, for example: “We earn enough for what we need and some of what we want, and we make choices about the rest.”
- “Why does my brother have more saved?” “Everyone’s goal and timing are different. Let’s look at your plan, not his.”
- “Are we going to be okay?” “Yes. The grown-ups have a plan, and your job is to be a kid.” If money is genuinely tight, see How to Talk to Kids When Money Is Tight.
- A child gets upset when a goal slips. “That’s disappointing. What’s one thing we could change: the amount, the date, or the goal?”
For a conversation starter tied to a specific moment, try the Money Conversation Generator.
Printable checklist
Copy or print this list for each meeting:
- ☐ One win from each person
- ☐ Current goal balance and next contribution
- ☐ One upcoming family decision
- ☐ Allowance payday and assigned expenses
- ☐ Subscriptions or renewals to review
- ☐ Account or fraud concern
- ☐ One question from each child
- ☐ Action, owner, and due date
Print this agenda strip too:
Printable meeting agenda (fill-in)
One sheet per meeting. Keep them in a folder to see progress over the year.
- ☐ Date ________ Time keeper ________
- ☐ Win from each person: ________
- ☐ Goal: ________ Target $____ Saved $____ Next step ________
- ☐ Upcoming choice: ________ Budget $____ Options: A ____ B ____
- ☐ Allowance payday ____ Anything to change? ________
- ☐ Renewals coming up: ________
- ☐ Questions to look up: ________
- ☐ One action: ________ Owner ________ Due ________
What not to do
- Do not blame a child for adult financial stress.
- Do not require children to solve essential household bills.
- Do not compare siblings’ balances or personalities.
- Do not turn every question into a lecture.
- Do not share passwords, full account numbers, or private documents.
The FDIC notes that family meetings can teach children about financial choices when adults use age-appropriate explanations. See Teaching Young People About Money.
Generate a discussion prompt with the Money Conversation Generator and find more practice in Family Money Activities.
Sources
- FDIC: Teaching Young People About Money
- Council for Economic Education: Survey of the States
- Consumer Financial Protection Bureau: Money as You Grow
- Consumer Financial Protection Bureau: Building blocks to help youth achieve financial capability (2016)
This article is for educational purposes and does not provide individualized financial, tax, legal, or investment advice. Example numbers are illustrations, not recommended amounts.
Leave a Reply