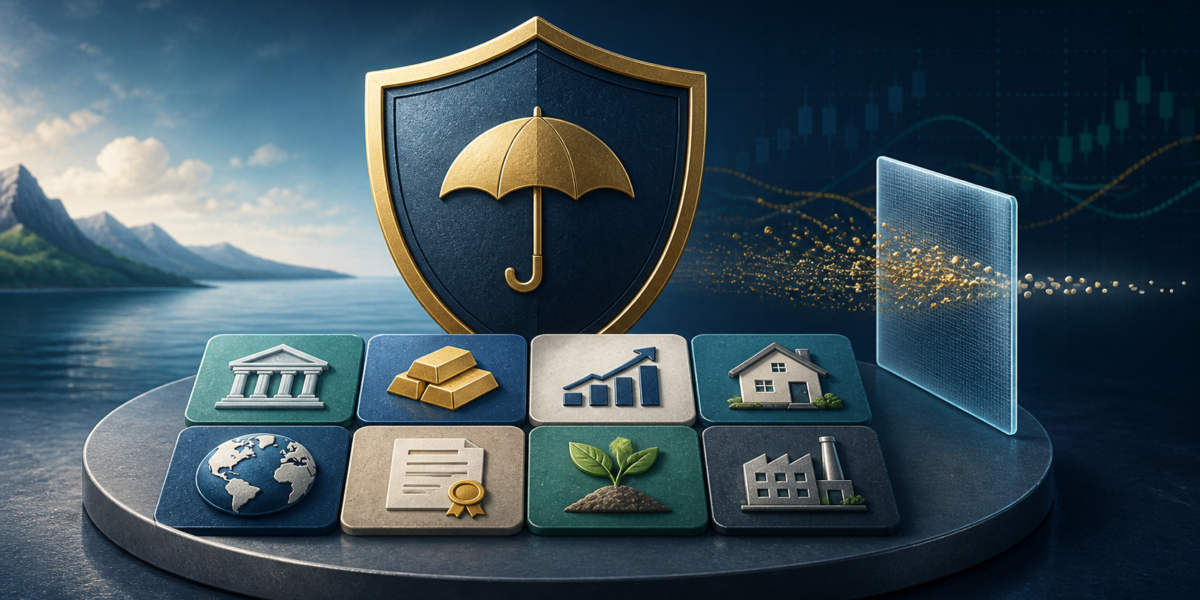
Investment returns receive attention, but risk and cost determine how much of those returns you may keep and whether you can stay invested through difficult markets.
Diversification and asset allocation can help manage risk, while disciplined fee review prevents small costs from quietly compounding against you.
This topic is part of our saving and investing guide, which connects the supporting steps into a broader financial plan.
Separate asset allocation from diversification
Asset allocation divides a portfolio among broad categories such as stocks, bonds, and cash. Diversification spreads holdings within and across categories. Owning several funds does not guarantee diversification if they hold the same companies.
Connect risk to time horizon
Market risk is easier to tolerate when a goal is far away and harder when withdrawals are near. Risk tolerance includes both willingness and financial ability to withstand losses.
Understand what diversification cannot do
Diversification can reduce concentration risk, but it cannot guarantee gains or prevent losses during broad market declines. Every investment involves risk.
Read the full cost
Look beyond a headline expense ratio. Review sales loads, advisory charges, account fees, trading costs, surrender charges, and tax effects. Ask how a professional is compensated.
Rebalance deliberately
Market movement can shift a portfolio away from its target. Rebalancing restores the intended risk level, but trades can create fees or taxes. Review infrequently and with a written policy.
Check holdings beneath the fund names
Imagine owning three funds that all concentrate on the same large companies. The number of funds increased, but exposure to those companies may still dominate. Compare holdings and asset categories across the portfolio rather than assuming different fund names provide different risks.
Translate a percentage fee into dollars
On a constant hypothetical $20,000 balance, a 0.25% annual charge is $50 and a 1% charge is $200. The $150 difference illustrates one year’s cost before changes in value or other charges; it is not a return projection. List fund expenses and separate account or advice fees so you understand the total.
Write a portfolio review note
Record the intended allocation, actual allocation, overlapping holdings, and each fee source. Compare similar services and risks before deciding a higher-cost option is unjustified. If changes would involve selling, review transaction costs and possible tax consequences before acting. Use the beginner investing guide for account setup; use this review to examine what is already held.
Frequently asked questions
Do more funds mean more diversification?
Not necessarily. Compare underlying holdings, sectors, asset classes, and geographic exposure for overlap.
Are lower fees always better?
Cost matters, but compare products with similar objectives, services, risks, and features rather than using one number alone.
Authoritative resources
This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax, legal, or credit advice. Consider consulting an appropriately qualified professional about your circumstances.
Leave a Reply