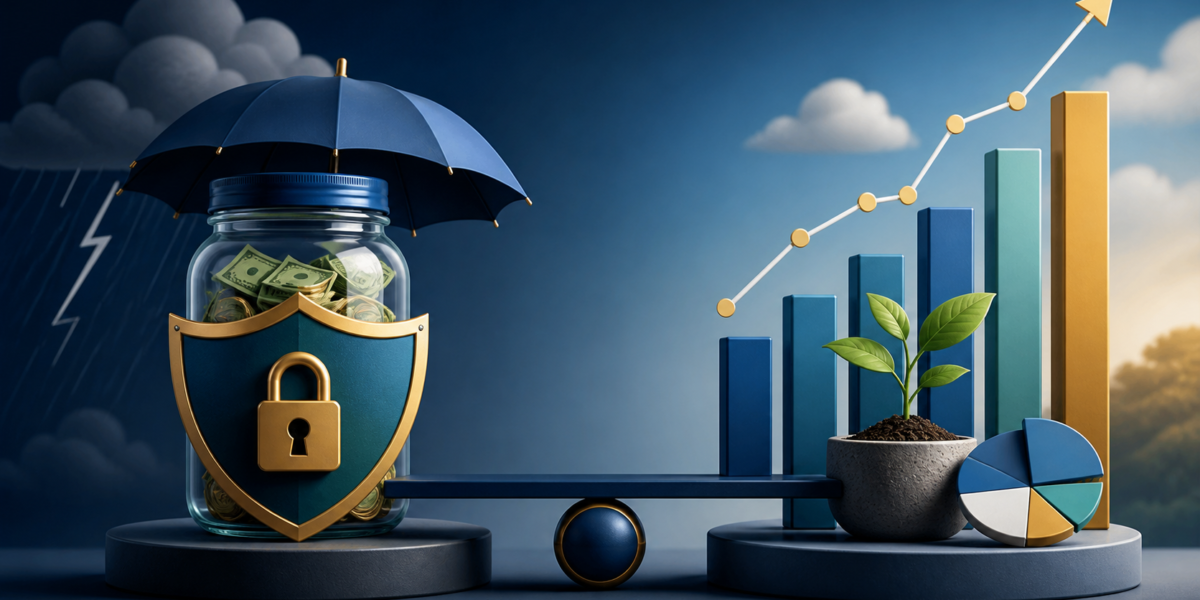
Saving and investing both support future goals, but they solve different problems. Savings provides stability and access; investing accepts market risk in pursuit of long-term growth.
The right order depends on urgency, debt cost, workplace benefits, time horizon, and how much volatility you can tolerate.
This topic is part of our saving and investing guide, which connects the supporting steps into a broader financial plan.
Protect immediate obligations
Keep bills and minimum debt payments current. If a small surprise would force new high-cost debt, build a starter emergency cushion before taking significant market risk.
Understand the employer match
A workplace retirement match can be valuable compensation. Learn the formula, eligibility, vesting, and contribution rules. Consider the match alongside the need for near-term cash reserves.
Address expensive debt
High-interest revolving debt can cost more than a reasonable expected investment return, which is never guaranteed. Compare the debt’s certain rate with the uncertain potential return and your liquidity needs.
Match the tool to the timeline
Money needed soon generally belongs in an accessible lower-risk account. Long-term goals may have time to absorb market declines and may be appropriate for a diversified investment plan.
Use a blended approach
The decision does not have to be all-or-nothing. You might fund a starter reserve, capture available match, attack expensive debt, then increase both emergency and retirement contributions over time.
Name the risk your next dollar needs to cover
Consider two households with the same spare $200. One has no accessible cash and a car needed for work; the other has a reserve but has not started a long-term investing plan. Identical income does not make their next step identical. Identify the expense or goal that would suffer if the money lost value or became hard to access.
Divide the decision into separate pots
Write down cash reserved for near-term bills, predictable expenses, unexpected setbacks, and long-term goals. Do not count the same $1,000 as both next month’s rent and an emergency reserve. Money assigned to a known expense should remain visible when judging how much is available to invest.
Use a trigger for the next change
Set a review point, such as reaching a chosen cash cushion or paying off a particular high-cost balance. At that point, revisit the split between saving and investing. This creates a repeatable decision rather than a permanent instruction to put every extra dollar in one place.
Frequently asked questions
How large should my emergency fund be before investing?
Use a layered target based on essential expenses, job stability, deductibles, and household risk rather than a universal number.
Can I invest my emergency fund?
Market losses can coincide with job or economic stress. Emergency funds generally prioritize safety and access over return.
Authoritative resources
This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax, legal, or credit advice. Consider consulting an appropriately qualified professional about your circumstances.
Leave a Reply