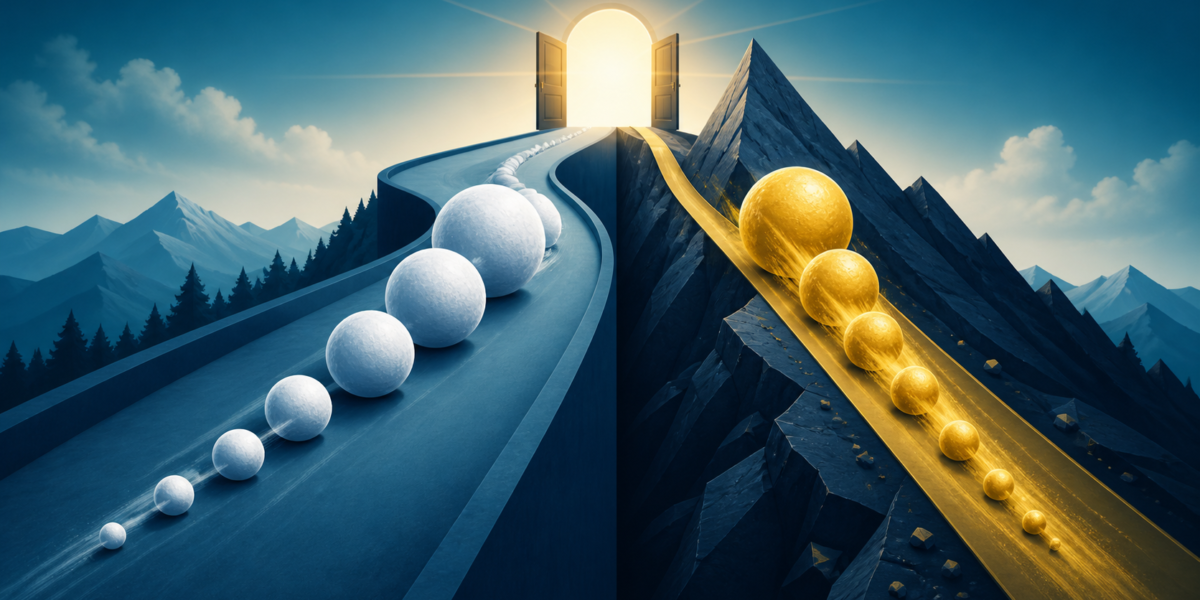
Two popular payoff methods solve different problems. The debt avalanche prioritizes interest cost, while the debt snowball prioritizes quick visible wins.
Neither method works unless minimum payments remain current and the extra payment is repeated consistently.
This topic is part of our credit and debt management guide, which connects the supporting steps into a broader financial plan.
How the avalanche works
List debts from highest interest rate to lowest. Pay required minimums on every account and direct extra money to the highest-rate balance. When it is gone, roll that payment into the next debt. This generally minimizes interest.
How the snowball works
Order debts from smallest balance to largest regardless of rate. Target the smallest while maintaining other minimums. Early eliminations may provide motivation and simplify the number of monthly payments.
Compare the real tradeoff
The avalanche is mathematically efficient; the snowball can be behaviorally encouraging. Estimate payoff time and interest under both, but also consider which plan you are most likely to continue through setbacks.
Protect the plan
Keep a starter emergency cushion, stop adding new revolving balances, automate minimum payments when safe, and send windfalls according to a written rule. Contact creditors early if payments become difficult.
Choose and commit
Select one method, document the order, and review progress monthly. A hybrid can target one small balance for momentum before switching to the highest rate. Avoid constant strategy changes triggered by emotion.
See why the payment order differs
Imagine Card A has a $600 balance at 12% APR and Card B has a $2,400 balance at 25% APR. After paying both required minimums, the snowball directs extra money to Card A; the avalanche directs it to Card B. The first prioritizes removing a balance sooner, while the second targets the more expensive rate.
Compare methods with the same payment budget
Use identical balances, rates, minimums, and monthly extra payment in both calculations. Otherwise, a faster result may come from contributing more, not from the method. Promotional rates, fees, new purchases, and changes to minimum payments can alter the estimate.
Set a rule for the first payoff
When an account reaches zero, redirect its former payment to the next target instead of absorbing that money into spending. Check the next statement for residual charges. If essentials or minimums become unaffordable, reassess the total payment budget before debating which extra-payment order is best.
Frequently asked questions
Should secured debt be included?
Prioritize obligations by consequence as well as rate. Housing, transportation, taxes, and court-ordered obligations may require specialized planning.
What if minimum payments are unaffordable?
Contact creditors promptly and consider reputable nonprofit credit counseling. Do not rely on promises that accurate debts can simply be erased.
Authoritative resources
This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax, legal, or credit advice. Consider consulting an appropriately qualified professional about your circumstances.
Leave a Reply