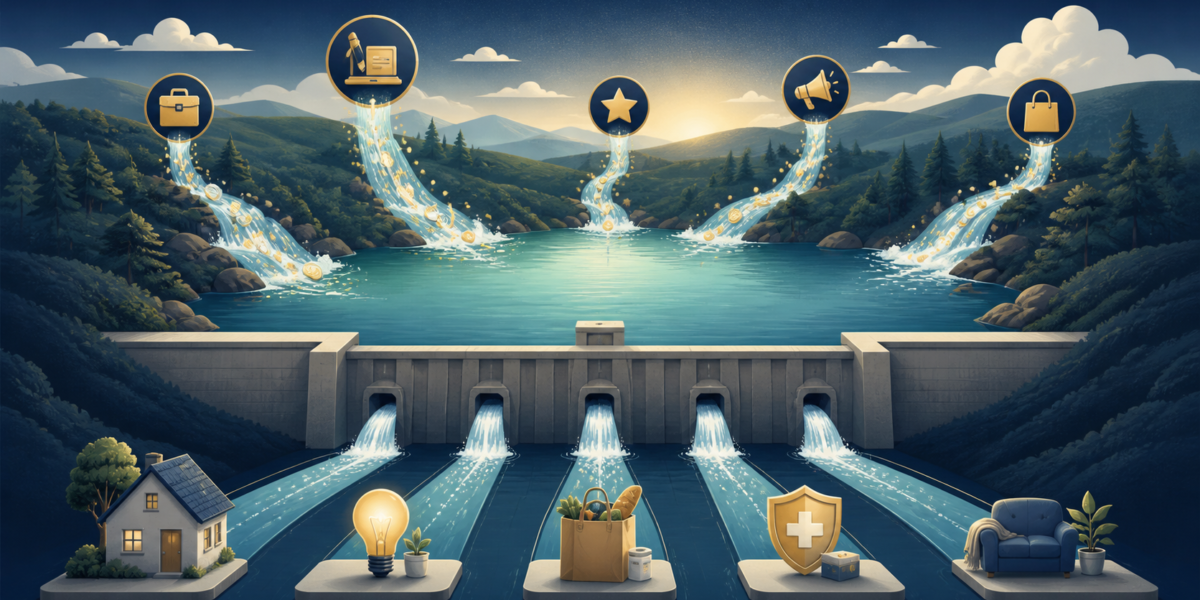
When income arrives on uneven dates, a monthly budget can look balanced while the bank account runs short on Tuesday. This guide shows how to build a rolling weekly cash-flow calendar: the order in which cash arrives and bills leave. The second half covers how to turn variable earnings into a steadier personal paycheck with a low-month baseline and a smoothing buffer: jump to the steady-paycheck system.
1. Start with spendable cash today
Write down the money currently available for household bills. Exclude funds already reserved for taxes, business obligations, or another specific purpose. Check pending transactions so the same money is not committed twice. A savings balance is not automatically available simply because it appears in the same banking app.
2. Put deposits on expected dates
List wages, client payments, benefits, and other expected receipts by week. Label uncertain payments clearly. An invoice sent is not cash received, and a usual payment date is not a guarantee. Keep a conservative version of the calendar that excludes receipts you cannot rely on yet.
3. Add withdrawals when they will happen
Enter housing, utilities, minimum debt payments, transportation, food, insurance, and other commitments in the weeks they are likely to leave the account. Include automatic transfers and annual or quarterly bills. A due date may differ from the date an automatic payment is initiated, so confirm both.
4. Carry each week’s balance forward
Use this formula: opening available cash + receipts − outflows = closing available cash. The closing amount becomes the next week’s opening amount. Keep restricted reserves outside this calculation unless you explicitly decide they are available for that expense.
A four-week example
Begin with $400. In week one, receive $900 and pay $1,100, leaving $200. In week two, receive $300 and pay $600, leaving a projected shortfall of $100. Week three brings $1,500 with $800 of outflows, and week four brings $300 with $500 of outflows. The month ends at a projected $400, yet week two still needs attention. Later income does not prevent an earlier payment from failing.
5. Respond to the earliest shortfall
Check whether a bill date can be changed by agreement, a discretionary purchase can wait, or an expected receipt can be confirmed. Do not simply move a required payment in your worksheet without arranging it with the provider. If the gap remains, contact affected providers before payments are missed and reassess the commitments the income can support.
6. Refresh the calendar every week
Replace estimates with cleared amounts, move delayed receipts to their new expected dates, and add another week at the end. Record why an estimate changed. After several cycles, repeated gaps can show whether the problem is timing, an unrealistic income assumption, or spending that exceeds available resources.
Common calendar mistakes
Do not treat an available credit limit as income, count transfers between your own accounts as new earnings, or include the same tax reserve in two places. Keep an uncertain invoice visible without relying on it to cover a fixed bill. Recheck pending card and bank transactions before deciding an apparent surplus is free to spend.
Turn uneven income into a steadier paycheck
The calendar handles timing. The longer-term fix is to stop spending each deposit as it lands and pay yourself a consistent amount instead. Stability comes from separating the earning pattern from the spending pattern.
Build from the low month
Review at least six to twelve months of take-home income when possible. Identify a conservative low month, a typical month, and a strong month. Base recurring commitments on the low month, not the average.
Create three destinations
- A tax reserve for income that has no tax withheld.
- An income-smoothing buffer for lean months.
- A spending account that receives a consistent scheduled transfer.
This turns volatile deposits into a steadier personal paycheck. The weekly calendar then checks whether that transfer, plus upcoming bills, can clear on time.
Give strong months an order
Refill the tax reserve first, then rebuild the smoothing buffer, catch up essential maintenance or insurance costs, and only then accelerate flexible goals. Without an order, a strong month can quietly become a new spending baseline.
Plan for known irregular costs
Annual premiums, holidays, equipment, slow seasons, and quarterly taxes are not emergencies. Use sinking funds so the emergency fund remains available for truly unexpected events.
How the calendar and the buffer work together
A calendar reveals when cash is needed. A smoothing buffer helps fund a steadier transfer despite uneven earnings. Use the Irregular Income Stabilizer to explore that longer-term structure; continue using the weekly calendar to check whether upcoming payments can clear.
Frequently asked questions
Should I budget using average income?
An average can hide low-month risk. Use it for planning, but base recurring commitments on a conservative month.
How large should an income-smoothing buffer be?
Start with several expected low-month shortfalls, then adjust for seasonality, dependents, and how quickly income can recover.
Are annual bills emergencies?
No. Predictable premiums, taxes, holidays, and equipment belong in sinking funds.
Source and next step
The CFPB’s Your Money, Your Goals toolkit includes a cash-flow budget. Gather this week’s balances, receipts, and bill dates and use those records for your first calendar. This article provides general education, not individualized financial or tax advice.
Related planning resources
Use the CFPB cash-flow worksheet for a written calendar, and the CFPB budgeting resources for spending plans more broadly. Review the IRS Self-Employed Individuals Tax Center for tax obligations. For the wider household plan, see our budgeting and cash-flow guide, sinking-fund guide, and emergency-savings guide.
Leave a Reply