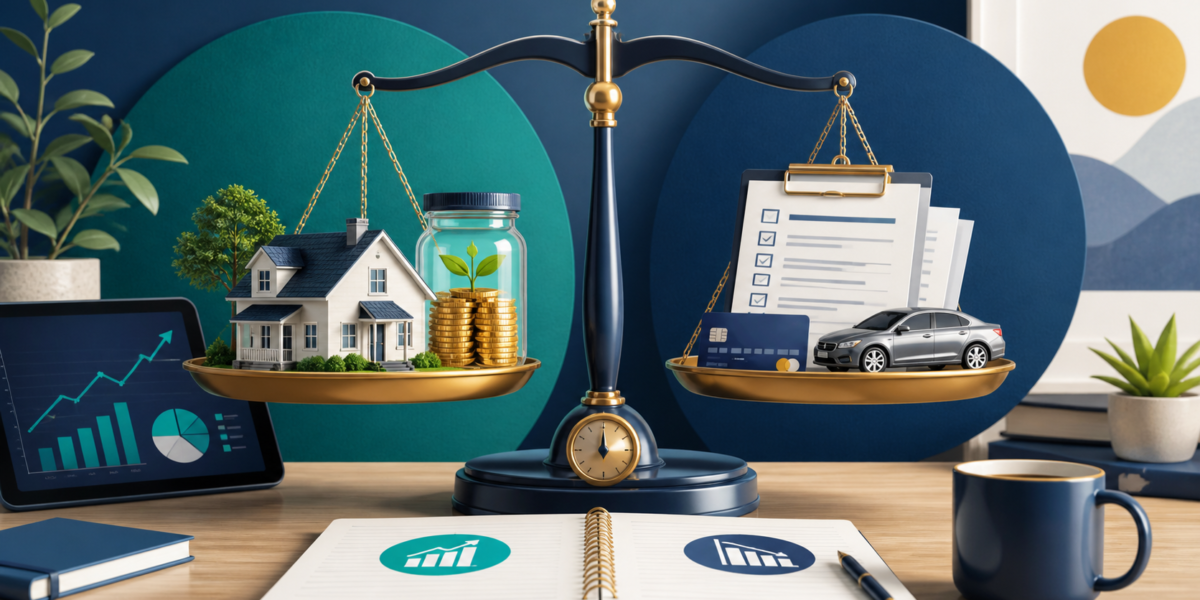
Net worth is a simple snapshot: what you own minus what you owe. It cannot measure your character or capture every part of your financial life, but it can show whether your overall position is strengthening over time.
Used alongside cash flow and savings, net worth can help you decide whether the next dollar should build reserves, reduce debt, or support a long-term goal.
This topic is part of our strong financial foundation guide, which connects the supporting steps into a broader financial plan.
Start with a complete list of assets
List cash accounts, savings, investments, retirement accounts, and the realistic current value of property you could sell. Use current statements and conservative values. Avoid counting future wages or possessions that have little resale value.
List every liability
Record credit-card balances, personal and student loans, auto debt, mortgages, tax obligations, and other amounts owed. Use current payoff balances when available rather than relying on memory.
Run the calculation
Subtract total liabilities from total assets. A negative result is not a verdict; it is a baseline. Many households start below zero after education, a home purchase, or a difficult season. What matters is the direction and the decisions behind it.
Track the trend without obsessing
Update the number quarterly or twice a year. Monthly market swings can distract from the bigger picture. Look for durable progress: growing liquid savings, falling high-cost debt, and consistent retirement contributions.
Turn the number into an action plan
Identify the one category with the greatest practical leverage. Building a starter emergency fund may prevent new debt. Paying down an expensive balance may improve cash flow. Increasing workplace-plan contributions may strengthen long-term assets.
A worked balance-sheet example
Suppose cash is $6,000, retirement savings are $24,000, and a car’s estimated resale value is $10,000. Assets total $40,000. If the car loan is $7,000 and other debt is $5,000, liabilities total $12,000 and net worth is $28,000. The $6,000 cash balance still matters separately: the rest may be difficult or costly to access.
Avoid double-counting equity
Either list a property’s full estimated value and its loan separately, or use equity as a single net amount. Do not enter equity as the asset and subtract the same loan again. Likewise, a transfer between two accounts changes where money sits, not total net worth.
Explain the change between snapshots
Keep valuation dates consistent. When the total changes, separate new saving, debt repayment, and market or property-price changes. A rising investment balance can improve net worth while cash reserves remain inadequate. Record one action for the weakest part of the balance sheet, rather than treating the total as spendable money.
Frequently asked questions
Does a home count toward net worth?
Yes. Use a reasonable current value and subtract the associated mortgage balance. Remember that home equity is not as liquid as cash.
How often should I calculate net worth?
Quarterly or semiannually is enough for most people. Consistency matters more than frequency.
Authoritative resources
This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax, legal, or credit advice. Consider consulting an appropriately qualified professional about your circumstances.
Leave a Reply