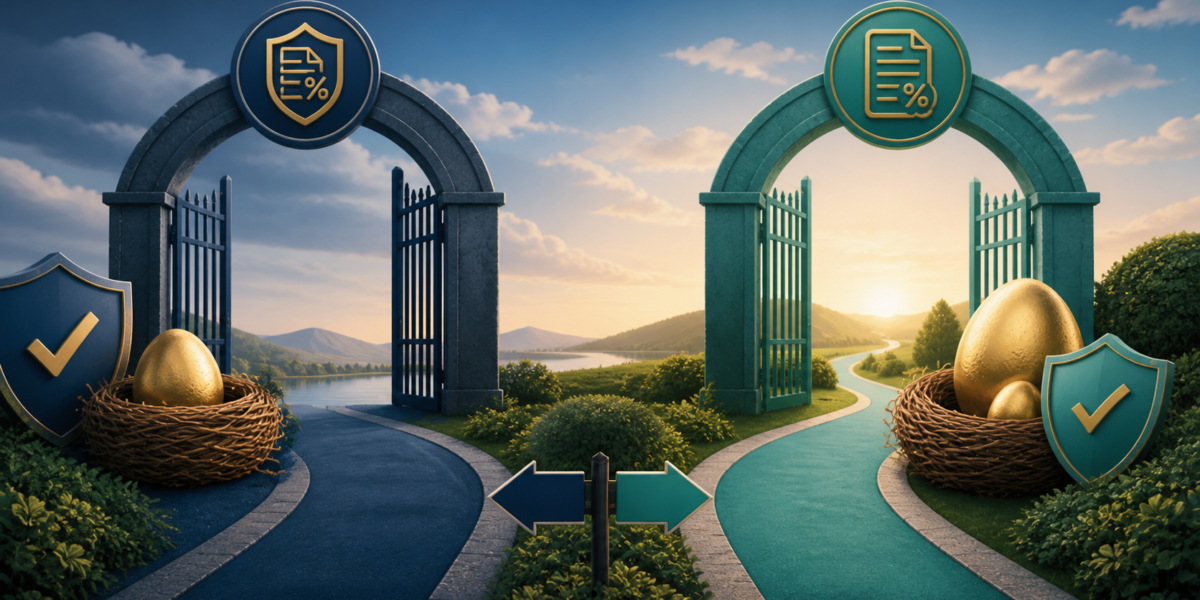
Roth and traditional retirement accounts offer different tax timing. Traditional contributions may provide a current tax benefit depending on the account and your circumstances; Roth contributions are generally made after tax, with qualified distributions potentially tax-free.
The choice is not simply about age. It involves current and expected tax situations, eligibility, plan features, withdrawal rules, and the value of diversification across tax treatments.
This topic is part of our retirement planning guide, which connects the supporting steps into a broader financial plan.
Separate IRAs from workplace accounts
A Roth IRA is not the same as a designated Roth 401(k). Income limits, contribution limits, employer matching, required distributions, loans, and withdrawal rules can differ. Identify the exact account under consideration.
Compare the tax timing
Traditional accounts generally defer tax on eligible contributions or earnings until distribution. Roth contributions do not produce the same upfront deduction, but qualified distributions can be tax-free when requirements are met.
Review eligibility and limits
IRA deductions and Roth IRA contribution eligibility may depend on income, filing status, and workplace-plan coverage. Limits change. Use the current IRS materials for the tax year rather than an old article.
Consider future flexibility
Holding both pre-tax and Roth assets may provide more choices when managing taxable income in retirement. That benefit must be weighed against current cash flow and tax effects.
Avoid false precision
Future tax rates, income, law, and retirement spending are uncertain. Model more than one scenario and consult a qualified tax professional for conversions or complex situations.
Compare equivalent household costs
Separate the amount contributed from the change in take-home pay. A current tax benefit can make equal contribution amounts have different immediate cash-flow effects. When comparing scenarios, state whether you are holding the contribution or the household’s after-tax cost constant.
Make an account-specific worksheet
Record the account type, tax year, contribution eligibility, potential deduction, withdrawal conditions, and employer-plan features. Keep IRA rules separate from workplace-plan rules. Use the current IRS resources below to check the specific case instead of applying a rule heard about a different account.
Identify which assumption could change the answer
Test a lower and higher future tax situation without treating either as a forecast. Changes in earnings, filing status, retirement income, or law can affect the comparison. A contribution choice and a conversion of an existing balance are different decisions; a conversion requires its own review of the tax cost and available cash.
Frequently asked questions
Can I contribute to both Roth and traditional accounts?
Often yes, but combined limits and eligibility rules apply. Workplace accounts and IRAs follow different rules.
Is Roth always better for younger workers?
No. Time horizon matters, but current deductions, income, tax rates, plan features, and future uncertainty also matter.
Authoritative resources
This article is for educational and informational purposes only and does not constitute individualized financial, investment, tax, legal, or credit advice. Consider consulting an appropriately qualified professional about your circumstances.
Leave a Reply